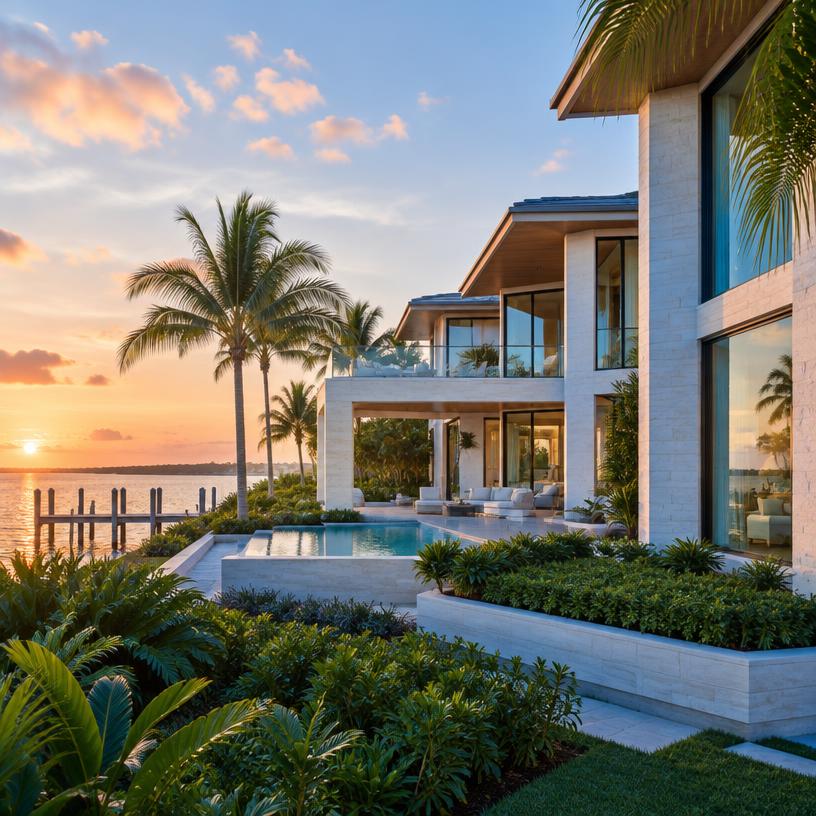
Oceanfront Palm Beach estate at golden hour

Buyer's Guide · Palm Beach County

Buy with a plan, not on impulse.

A clear path through Palm Beach County's market—from first search to keys in hand—so you move confidently in one of Florida's most sought-after regions.

215 means good news is coming. Buying a home here should feel that way too—prepared, informed, and on your terms.

Palm Beach County spans oceanfront estates, golf-course communities, walkable downtowns, and fast-growing western suburbs. The range is a strength, but it also means the right preparation matters. This guide walks you through the decisions that shape a successful purchase: where to look, how to finance, what to inspect, and how to stay organized from offer to closing.

Tips from the field

Five things to get right early.

Start with the life, not the listing

Before you tour, define the daily rhythm you want—commute, schools, boat access, walkability, evenings out. In Palm Beach County, two homes at the same price can offer completely different lifestyles a few miles apart.
Know your true budget early

Get pre-approved before you fall in love with a home. Florida carries costs that surprise out-of-state buyers: insurance, wind mitigation, HOA or club dues, and possible flood-zone requirements that affect both monthly cost and financing.

Learn the coastal-vs-western trade-offs

East of I-95 means older charm, walkable downtowns, and ocean proximity—often with smaller lots and higher prices. Western communities offer newer construction, larger lots, and golf-course living at a different price point.

Understand insurance and inspections

In South Florida, a four-point inspection, wind mitigation report, and roof age can drive both insurability and price. Order inspections during the inspection period and confirm a property is insurable before removing contingencies.

Time the local market, not just the calendar

Seasonal demand peaks during winter months when northern buyers arrive. The right time to buy is when the right home meets your goals—your agent can tell you whether a listing is priced for the season or for a quick sale.

Where to look

Find your corner of the county.

Explore all neighborhoods

Financing the purchase

From pre-approval to keys.

Florida's financing path looks familiar, but local costs—insurance, flood zones, and club dues—change the math. These four steps keep you ready at each stage.

01

Get pre-approved

A lender reviews income, assets, and credit to give you a letter stating how much you can borrow and at what rate. In a competitive market, sellers expect a pre-approval—often a strong one—to accompany an offer.

02

Compare loan programs

Conventional, FHA, VA, and jumbo loans each fit different buyers. Florida also has first-time-buyer and down-payment assistance programs worth comparing. Your lender can model monthly costs across programs.

03

Budget for Florida-specific costs

Beyond principal, interest, taxes, and insurance, plan for windstorm and flood coverage, HOA or club dues, and special assessments. Ask whether flood insurance is required and factor it into your total monthly cost.

04

Lock and close

Once you're under contract, your lender orders the appraisal and finalizes the rate lock. Florida closings use a title company or attorney; funds are wired, the deed is recorded, and you receive the keys.

We're happy to recommend trusted local lenders and title professionals. These introductions are a starting point—always compare options and confirm the figures that fit your situation.

Your checklist

Track every step to closing.

Your progress saves automatically in this browser, so you can return any time. Work through it in order, and reach out whenever a question comes up.

0 of 17 complete0%

Prepare

Search

Offer

Due diligence

Finance

Close

Ready to start?

Let's find the home that fits your next chapter.

Tell us your goals and we'll shape the search around them—neighborhoods, budget, timing, and the lifestyle that matters most to you.